Bitumen buyers don’t usually spend much time thinking about crude oil pipelines. But when a disruption occurs far upstream at the crude supply level, it can eventually work its way down to the bitumen market, particularly in regions where refiners depend heavily on a specific type of crude to produce it. That’s the situation now developing in parts of Europe, following reports that Saudi Arabia’s state oil producer will not supply some European refiners with October loading term crude.
This article explains what has been reported, why crude supply matters for bitumen production specifically, and what European and international buyers should watch as the situation develops. It’s worth being clear from the outset: this is a potential supply chain risk, not a confirmed bitumen shortage. The distinction matters, and we’ll keep it clear throughout.
What Is Happening With Saudi Crude Supply?
In mid-September, Saudi Arabia’s major East West crude export pipeline was reportedly attacked, following weeks of wider regional tension connected to the ongoing conflict involving Iran-aligned forces. In the aftermath, market sources indicated that Saudi Arabia’s state-controlled oil producer informed at least a few European refiners that they would not receive their usual October loading term crude allocation, following earlier disruptions that had already affected September loading volumes.
At the same time, broader shipping activity through the Strait of Hormuz, a critical corridor for Middle East crude exports, has reportedly declined sharply, with vessel traffic falling to a fraction of typical levels amid increased attacks on commercial shipping in the area.
Taken together, these developments point to a genuine disruption in the flow of Middle Eastern crude toward some European destinations. What remains less certain is how significant, and how long-lasting, the downstream effects will be.
Why Crude Supply Matters for European Bitumen Availability
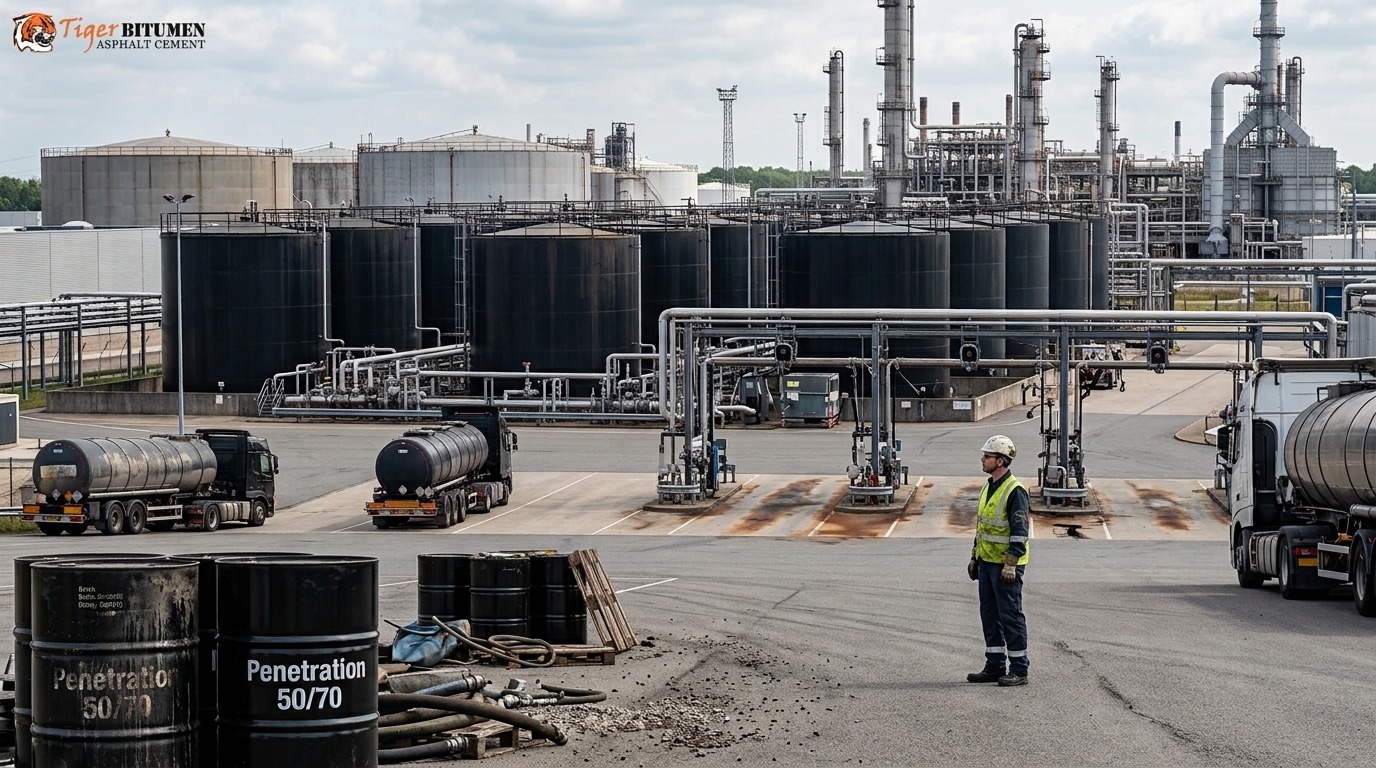
Bitumen isn’t manufactured independently; it’s produced as part of the broader crude refining process, typically from the heaviest fraction left over after lighter products like gasoline, diesel and jet fuel have been extracted. Not all crude oils are equally suited to this. Heavier, sourer crude grades, many of which originate from the Middle East, tend to yield significantly more bitumen than lighter, sweeter crudes.
This means a refinery’s crude slate directly shapes how much bitumen it can produce. A refiner that relies heavily on Middle Eastern crude for its heavy residue can typically produce solid bitumen volumes. If that refiner has to substitute in a different crude type because its usual supply has been disrupted, its bitumen output can be affected, even if its overall crude throughput stays roughly the same.
This is the mechanism connecting crude pipeline disruption thousands of kilometers away to a possible tightening of European bitumen availability at a European terminal. It’s an indirect link, but a real one, and it’s why refiners’ crude sourcing decisions are worth watching by bitumen buyers, not just crude traders.
What This Could Mean for European Bitumen Supply
To be clear about what has and hasn’t been established: the reported development is a reduction in term crude supply to a small number of European refiners. It is not, at this stage, a confirmed reduction in European bitumen output or availability.
What can reasonably be said is this: refiners with a crude slate that leans heavily on Middle Eastern grades are more exposed to this kind of disruption than those with more diversified sourcing. If affected refiners are unable to secure comparable substitute crude quickly, their bitumen yield could be affected in the weeks ahead. Whether that translates into a noticeable tightening of regional bitumen supply will depend on how widespread the crude disruption turns out to be, how long it lasts, and how effectively affected refiners can adjust.
This is a scenario worth monitoring rather than a confirmed outcome to plan around as settled fact.
European Refinery Operations and Regional Bitumen Supply
The crude supply question arrives at a moment when several other European refinery-level developments are already shaping regional bitumen availability, independent of the Saudi crude situation.
Planned refinery maintenance is one factor. Several European refiners have either deferred or are approaching scheduled turnaround work this autumn, in some cases reportedly delaying planned shutdowns because strong margins on other refined products such as diesel and jet fuel have made it more attractive to keep units running. Where turnarounds do go ahead as planned, they temporarily reduce a refinery’s total output, including bitumen, for the duration of the work.
Regional production trends are also relevant context. Some Northern European markets have seen bitumen output run below prior-year levels for parts of 2026, reportedly linked to feedstock availability constraints rather than demand issues. This suggests that feedstock tightness affecting bitumen yield isn’t an entirely new dynamic in the region. It’s a condition some markets have already been navigating this year, and the Saudi crude development adds a further variable to watch rather than introducing an isolated new risk.
For buyers tracking regional supply conditions, broader bitumen availability by region can provide useful context when comparing different sourcing markets.
Why Mediterranean Bitumen Supply Flows Matter
The Mediterranean plays a particularly important role in this picture because it currently looks somewhat different from the rest of the region. Bitumen export availability from parts of the Mediterranean, notably Spain, has reportedly been increasing recently, helped by regular deliveries of bitumen-yielding crude from South American sources rather than Middle Eastern grades. That crude diversification appears to be supporting Spanish refinery output even as some other European markets navigate tighter feedstock conditions.
This matters for buyers because it illustrates a broader point: the impact of any single crude disruption is not uniform across Europe. Refiners with diversified, non-Middle Eastern crude slates may be comparatively insulated from the current Saudi supply issue, while those more dependent on Middle Eastern grades carry more exposure.
For buyers, this means regional and even refinery-level differences are worth understanding, rather than assuming a single “European bitumen market” narrative applies uniformly.
What European and International Buyers Should Watch
A few developments are worth tracking in the weeks ahead:
- Whether the Saudi term crude disruption is resolved, extended, or expands to affect additional European refiners
- Whether affected refiners can secure alternative crude grades without a meaningful gap in bitumen output
- How Mediterranean export availability, particularly from Spain, evolves, given its apparent role in offsetting tighter conditions elsewhere
- Whether planned or deferred European refinery maintenance schedules change again as the autumn paving season progresses
- General regional price and premium movements, which can offer an early signal of tightening before availability issues become widely visible
None of these signals confirm a particular outcome on their own. Watched together, they give a more complete picture of whether the current crude disruption is likely to meaningfully affect bitumen supply, or whether it remains a contained, refiner-specific issue.
Practical Sourcing Considerations for Q4 2026
For procurement teams planning Q4 European bitumen purchases, a few practical steps can help manage uncertainty.
Look beyond the headline price. In a market with potential feedstock-driven supply risk, availability and lead time may matter as much as the per-tonne price, particularly for buyers with fixed project deadlines.
Understand your supplier’s crude exposure where possible. Refiners with diversified crude sourcing may be less exposed to this specific disruption than those heavily reliant on Middle Eastern grades.
Build in some lead-time flexibility. If feedstock-related tightness does materialize at a specific refinery or region, buyers with rigid, short-notice requirements will have the least room to adapt.
Keep an eye on regional differences. Mediterranean supply conditions currently look different from those in parts of Northern Europe. A sourcing strategy that assumes uniform European conditions may miss meaningful regional variation.
How Buyers Can Evaluate European Bitumen Availability
For buyers assessing European supply opportunities, it is useful to look at several indicators together rather than relying on a single market signal.
Crude availability is one part of the picture, but refinery operating rates, planned maintenance, regional export volumes, freight costs and supplier lead times can all influence the actual availability of bitumen for a specific destination.
Price movements can also provide useful context. Comparing current bitumen prices and market movements with changes in regional supply conditions can help procurement teams distinguish between a broader cost increase and a more specific tightening in physical availability.
This is particularly important when a crude disruption affects some refiners more than others. A reported reduction in crude supply does not automatically mean that every European loading point will experience the same impact.
Tiger Bitumen Perspective
Feedstock and crude supply developments like this one are a useful reminder that bitumen availability doesn’t only depend on bitumen-specific market conditions; it’s also shaped by decisions and disruptions further upstream in the crude supply chain.
Tiger Bitumen follows these developments as part of supporting international buyers with their sourcing decisions, and is available to discuss current market conditions, specification requirements, and delivery considerations with buyers assessing their options for the quarter ahead.
We don’t guarantee specific origins, fixed availability, or set pricing in advance of a genuine sourcing discussion, but we’re glad to help buyers think through how developments like this one might affect their particular procurement plans.
FAQs
Has Saudi crude supply to Europe been fully stopped?
No. Reports indicate that a small number of European refiners have been told they will not receive October loading term crude, following earlier disruptions to September loading volumes. This is a partial, refiner specific disruption rather than a full halt in Saudi crude exports to Europe.
Does reduced Saudi crude supply mean European bitumen will run short?
Not necessarily, and not yet confirmed. Reduced crude supply could affect bitumen yield at refiners heavily reliant on Middle Eastern crude grades, but whether this translates into a broader regional shortage depends on how the situation develops and how affected refiners adjust their sourcing.
Why does crude type matter for bitumen production?
Bitumen is produced from the heaviest fraction of crude oil remaining after other fuels are extracted. Heavier, sourer crude grades common from the Middle East typically yield more bitumen than lighter crude types, so a refinery’s crude slate directly affects how much bitumen it can produce.
Are all European bitumen markets equally affected?
No. Exposure varies by refiner and region, depending on how reliant each is on Middle Eastern crude. Some Mediterranean supply, for example, has reportedly benefited from non-Middle Eastern crude sources, which may make it comparatively less exposed to this particular disruption.
What should buyers do while this situation develops?
Monitor regional supply and price signals, maintain flexibility in lead times where possible, and consider discussing sourcing options with suppliers who track these developments, rather than assuming current tightness or current stability will necessarily continue.