Seasonal bitumen demand follows the calendar. Rain, frost, holidays, and budget years all influence when roads get built, and these factors do not occur at the same time everywhere. In the final quarter of the year, one region may be entering its busiest paving period while another is winding down for winter.
This guide sets out the seasonal factors that shape bitumen demand in different regions during Q4 2026 and how buyers can plan around them. It is a planning guide, not a demand forecast. It does not predict prices, volumes, or market direction. Sections based on this week’s reporting are marked as observations, while general explanations and procurement guidance are identified separately.
Why Seasonal Bitumen Demand Matters in Procurement
General explanation.
Road surfacing depends on suitable weather, while public and private works follow project calendars and budgets. Bitumen consumption can therefore show recurring seasonal patterns, although the timing and strength of those patterns vary by market. Buyers who understand the pattern in their own market can time purchases, storage and deliveries more deliberately.
Seasonal demand does not guarantee anything about price or availability. A busy season does not mean supply is short, and a quiet one does not mean supply is plentiful. Seasonal timing is one input alongside stock levels, refinery output, shipping and buyer budgets, and it works differently in each market.
For broader background on how weather patterns affect bitumen demand and supply planning, see our seasonal bitumen demand and supply planning guide.
Asia-Pacific: Seasonal Bitumen Demand Builds in Several Markets
Market observation. Asia-Pacific shows several seasonal patterns at once.
In Australia and New Zealand, demand increased in early spring as dry weather encouraged road construction and paving. Market participants expect it to keep rising through the construction season. Some buyers there sought cargoes from south China and Taiwan because Singapore-origin supply was limited.
In Vietnam, demand rose as the monsoon eased and the country entered its peak construction period. Importers said many projects previously delayed by budget constraints or wet weather had resumed and needed completing. Market participants said typhoon-related road damage is likely to add to fourth-quarter requirements. They also noted that budget limits could remain a challenge if prices continue to climb sharply.
Thailand shows that seasonal patterns do not always translate directly into demand. September is typically busy there, as contractors complete roadworks ahead of the new fiscal year on 1 October. Domestic demand was slower than expected, and market participants attributed this to elevated seaborne prices, tight supply, extended project deadlines and rainy weather.
In China, market participants pointed to the national holiday from 1 to 7 October. Sellers were focused on drawing down inventories and fulfilling term contracts ahead of it, while the Mid-Autumn Festival slowed buying slightly late in the week. In India, importers were seeking cargoes to restock ahead of the post-monsoon demand cycle, although consumption in the week itself remained limited.
Why this matters. Within one region, seasonal calendars can point in different directions. Buyers active in several Asia-Pacific markets need to look at each market’s own conditions rather than relying on a regional average.
West Africa: Dry Season Supports Road Activity
Market observation. In Nigeria, the reporting describes October as the start of the dry season, which market participants link to a lift in demand. Wet weather stalled paving across much of the country in August, and many end-users built inventories during that time. Some buyers are holding enough stock to cover demand through October. In Ghana, demand is understood to have strengthened in recent weeks, supported by extensive road construction projects.
General interpretation. Seasonal demand and purchasing demand are not the same thing. A buyer with stock already in the tank may not need to buy as soon as the weather improves, while a buyer with lower stock or earlier project starts may. Timing of new purchases depends on inventory as well as on the weather.
East and Southern Africa: Demand Builds Ahead of the Paving Season
Market observation. In South Africa, the onset of spring has begun to lift bitumen demand. Road paving activity typically accelerates from October, with higher activity often extending through the summer months. Several cargoes were heading to Durban ahead of the season, and regional suppliers reported increased activity. Domestic prices were steady this week. One domestic supplier expects prices to strengthen as demand rises, and other market participants are monitoring possible upward revisions in October. That is a market participant’s view and a signal to watch, not a forecast.
In East Africa, demand in Uganda, the Democratic Republic of Congo and South Sudan is reported to be emerging stronger as October demand picks up. In Kenya, demand was described as adequately met by trucked flows.
General interpretation. South Africa relies heavily on imported bitumen, so a seasonal rise reaches buyers through cargo schedules, port discharge, and storage. The timing of demand and the timing of supply are separate questions.
Europe and the Mediterranean: Seasonal Demand Winds Down
Market observation. Europe is at a different point in the cycle. Nordic demand is winding down as the region moves into winter, and market participants say demand from that region has started to wane. Some Scandinavian construction firms have already closed tenders for their 2027 term requirements. Buyers in North West Europe built inventories through September.
Elsewhere in Europe, activity has been slow to restart after the summer break. UK demand was subdued through much of September, although a group of incoming cargoes signalled a resumption, and market participants expect activity to pick up by the end of the month. French demand was also subdued in September, and suppliers there expect it to increase in October. Italian demand was reported to be strong in June and July before the summer pause and slower to emerge since, with market participants expecting a pick-up in the second week of October. Polish demand was described as the weakest in Europe.
In the Mediterranean, demand remained weak. North African buyers reported holding enough stock to cover October, after heavy buying of Greek cargoes in August and September. Libyan demand was held back by reduced construction budgets, and Algerian imports were slowed by delays in government permits. Some Spanish volume may look for outlets in North West Europe, where market participants are watching for demand to increase in October.
Why this matters. Europe is not one seasonal market. Northern buyers are heading into winter with stocks built, while some southern and western markets are working through a delayed restart. The reporting also shows that quiet demand does not mean nothing is happening. Winter and next-season term arrangements are already being planned in some places.
Regional Snapshot
A neutral summary of this week’s reporting. Not a forecast.
| Region | Seasonal pattern observed this week | Procurement consideration |
| Asia-Pacific | Construction activity increasing in Australia, New Zealand and Vietnam. Thailand’s demand is slower than expected. Holiday timing in China. | Monitor project timing, budgets, and cargo availability by market |
| West Africa | Dry season beginning in October. Some buyers hold stock built during the rainy season. | Compare existing stock with road-project schedules before ordering |
| East Africa | Demand strengthening in several inland markets. Kenya’s demand is met by trucked flows. | Check whether supply routes suit inland delivery timelines |
| Southern Africa | Spring lifting demand, with paving typically accelerating from October. Cargoes heading to Durban. | Plan import timing, discharge and delivery together |
| North and Central Europe | Nordic demand winding down. North West European buyers hold built-up stocks. Restart after summer slowdown in some markets. | Consider existing inventories and the seasonal slowdown |
| Mediterranean and North Africa | Demand is soft in parts of the region. Some North African buyers hold enough stock for October. | Monitor stock levels and import requirements |
How Seasonal Bitumen Demand Affects Procurement
General procurement guidance.
Seasonal bitumen demand affects procurement decisions in several ways. The exact effect depends on the buyer’s stock position, project schedule, supply route, and delivery requirements.
- Purchase timing. Buyers often try to secure supply before the busiest weeks, but stock already held can move the date at which a purchase becomes necessary.
- Competition for supply and logistics. When several buyers need product at once, cargo and vessel availability and terminal capacity can become constraints. This depends on the market and is not universal.
- Project scheduling. Projects that resume when the weather improves need bitumen on site by a specific date, which sets the deadline for ordering.
- Contract planning. Buyers heading into a quieter season may turn to next-year arrangements. Term and spot procurement can be assessed according to the buyer’s expected volume, flexibility and supply requirements.
Stock Levels, Lead Times and Delivery Planning
Seasonal demand does not mean the product is immediately at hand. Between a purchasing decision and bitumen at the project site sit several steps: cargo availability, vessel schedules, sea freight, port discharge, storage, inland delivery and documentation. Each adds time, and each can slip.
This week’s reporting shows how that can play out. Some Asian importers with urgent project needs found little or no Singapore-origin supply and sought alternative origins. Nigerian buyers with adequate stock could hold off. North African buyers with stocks covering October reduced their spot buying. In each case, the buyer’s position depended on stock and lead time as much as on the season.
The FOB price is also only part of the picture. A cargo’s delivered cost includes freight, route conditions, port charges, and delivery terms. Buyers planning around a seasonal peak may find that delivered-cost comparison matters more when timelines are tight.
A Practical Q4 Bitumen Procurement Checklist
General procurement considerations. They do not guarantee any market outcome.
Demand and Timing
- Expected project start dates and how firm they are
- Estimated bitumen consumption for the quarter
- Flexibility for changing project schedules, including weather delays and budget changes
Product
- Required grades and specifications
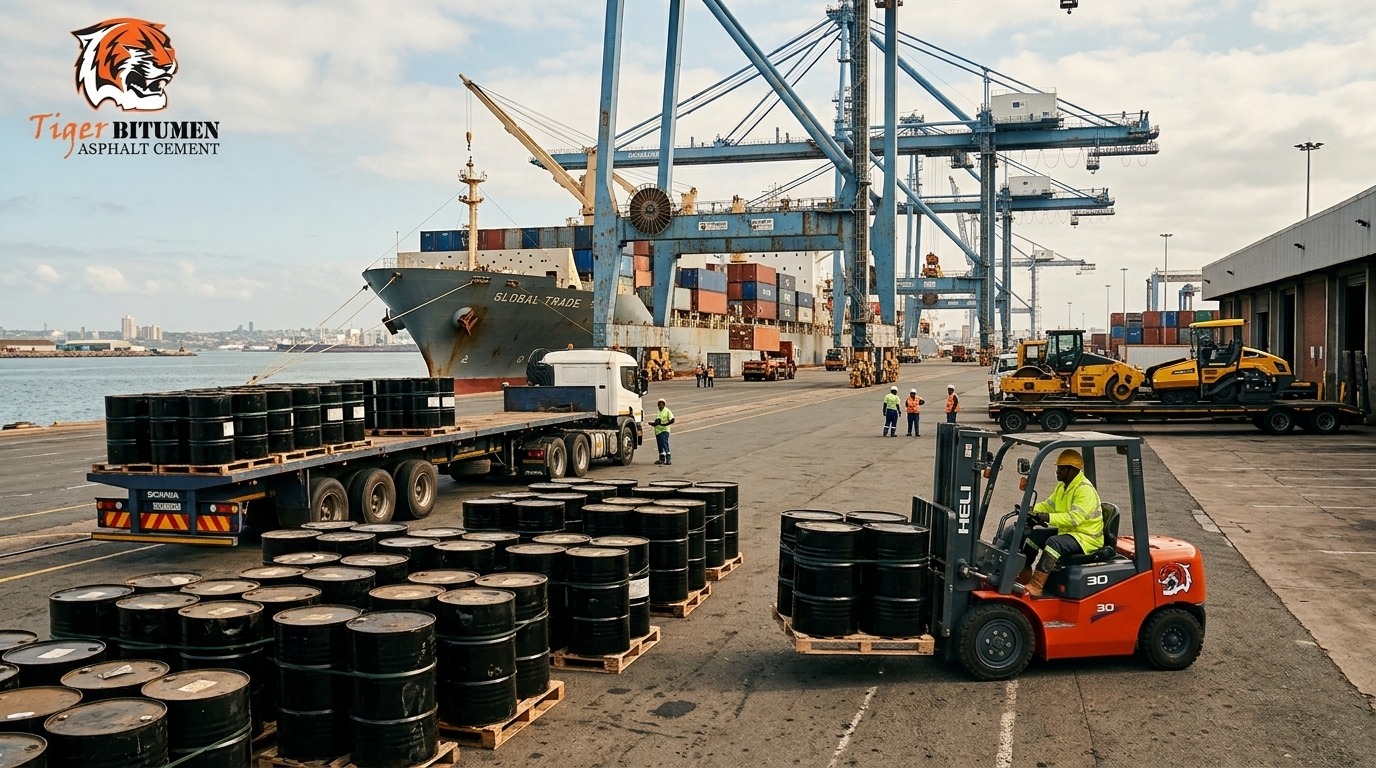
- Delivery format, such as bulk or drums
Buyers should confirm the required grades and specifications before requesting supply.
Stock and Reordering
- Current inventory across terminals and depots
- The reorder point, meaning the stock level at which a new order needs to be placed
- Available storage capacity
Supply and Logistics
- Supplier lead time, from order to loading
- Vessel and cargo schedules
- Port and terminal capacity for receiving the cargo
- Inland transportation to the project site
Compliance
- Documentation and compliance requirements at the destination, with time allowed for approvals
Working through the list early can show which items are the tightest constraints, whether that is stock, lead time, storage, or paperwork.
What Buyers Should Monitor Through Q4
These are signals to watch, not predictions of what will happen:
- The pace at which seasonal activity picks up in each buyer’s own market, and whether existing stocks are drawn down or topped up first.
- Stock levels among buyers and suppliers, including whether early-October demand draws on inventory built earlier.
- Cargo arrivals and vessel schedules into the ports the buyer relies on.
- Budget and funding conditions for public road projects, which market participants cited in Vietnam and elsewhere.
- Weather and disruption, such as rainy conditions or typhoon-related road damage, that can delay or add to project requirements.
- Holiday calendars, such as China’s early-October national holiday, which can change buying patterns around them.
- Price revisions and premium movements, including the October revisions that market participants in southern Africa are watching.
- Crude and fuel oil volatility, which this week’s reporting cited as influencing buyers’ timing in several markets.
Tiger Bitumen Perspective
Tiger Bitumen is an international bitumen supplier and exporter. We follow regional market developments and work with buyers on grade, specification, sourcing, shipment planning, and delivery requirements. Buyers mapping their fourth-quarter needs can contact us to discuss their requirements. Any supply discussion depends on the buyer’s specific needs and on current market conditions. This article is general commentary and does not constitute a price or availability offer.
Conclusion
Seasonal bitumen demand looks different in each region. In the reporting week, some markets were entering their busiest period, and others were winding down for winter. Some buyers held enough stock to wait, while others were seeking cargoes. Seasonality tells a buyer when work is likely to happen. It does not say what the market will do.
The most useful preparation is to know your own position: projects, consumption, grades, stock, storage and lead times. Buyers who compare offers on a delivered basis, allow time for logistics and documentation, and keep watching local signals will be better placed to plan Q4 requirements.