Bitumen supply starts with the crude oil a refinery chooses to run. Bitumen is made from the heaviest part of the barrel, and only certain crudes leave enough suitable material to make it. When those crudes become hard to obtain, bitumen output can fall even while refineries keep running and road-building demand stays strong.
That pattern has been visible in 2026. Disruption to shipping in the Middle East has tightened supplies of sour Middle Eastern crude into Europe and Asia. Market reporting has linked lower bitumen output in several countries to that shortage.
This article explains three things:
- why bitumen depends on these crudes;
- how refiners decide how much bitumen to make;
- what a feedstock shortage means for international buyers.
Where bitumen comes from in the barrel
Refining begins with atmospheric distillation, which separates crude oil into fractions by boiling range. The lighter fractions become products such as LPG, gasoline, jet fuel and diesel. The heavy material left at the bottom is called atmospheric residue.
That residue is then distilled again under vacuum. The lower pressure lets heavier components separate without excessive heat damaging them. Vacuum distillation recovers heavy gasoils and leaves behind vacuum residue, the main base material for paving bitumen.
Refiners make finished grades from this residue in several ways:
- Straight-run production. The hardness of the residue depends partly on how deeply the vacuum unit cuts into the crude. A deeper cut leaves a harder residue.
- Blending. Residues of different hardness can be blended to reach a target grade, such as a specific penetration grade bitumen.
- Air-blowing. Mild air-blowing can adjust the properties of some paving grades. More intensive blowing produces oxidized bitumen for roofing and industrial uses.
How much bitumen a refinery can make therefore depends on two things:
- how much vacuum residue its crude leaves;
- whether that residue has the properties needed for the grades the refinery sells.
Why “heavy” and “sour” matter
Heavy crude generally leaves more residue
Crude oils differ widely in density. The industry measures this with API gravity: the lower the API gravity, the heavier the crude. Heavy crudes generally contain a larger share of high-boiling material, so they tend to leave more vacuum residue. Light crudes usually leave relatively little, and most of their barrel becomes lighter fuels.
The link is general rather than exact, because residue yield also depends on the crude’s composition. A refinery that switches from a heavy crude to a light one may still run at full capacity. It will simply have much less material from which to make bitumen.
Heavy and sour are different properties
“Sour” describes crude with a relatively high sulphur content, while “heavy” describes density. They are separate properties, and some heavy crudes are low in sulphur. Sulphur itself does not make bitumen.
In practice, however, many heavy crudes traded internationally are also sour. That includes Middle Eastern grades widely used for bitumen production. This is why the industry often refers to “heavy sour crude” as bitumen feedstock. It is also why a shortage of sour Middle Eastern crude often means a shortage of bitumen feedstock.
Not every heavy crude makes good bitumen
Residue composition matters as much as residue volume. Bitumen performance depends on the balance between its main components: asphaltenes, resins and oils.
- Crudes whose residues have a suitable balance, often described as naphthenic, tend to produce bitumen with good binding and durability properties.
- Highly waxy, paraffinic crudes can leave residue that performs poorly as paving bitumen.
For this reason, refiners qualify specific crudes, or blends of crudes, for bitumen production. A replacement crude with similar density may still be unsuitable. This is why buying any available heavy crude does not automatically restore bitumen supply.
How refiners decide how much bitumen to make
Bitumen competes with other outlets for the residue
A refinery holding vacuum residue usually has more than one option for it:
- Bitumen, where the residue meets specification and there is demand.
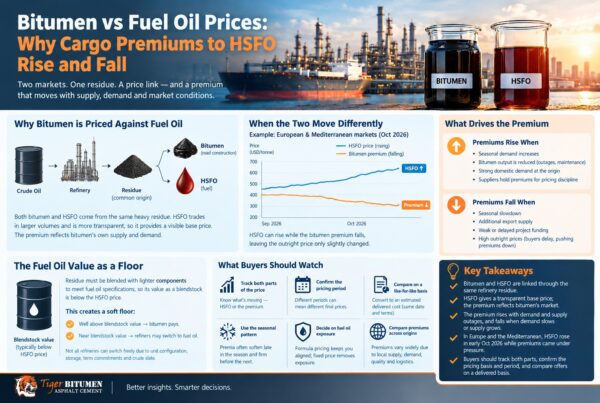
- Fuel oil, where the residue is blended into heavy marine or industrial fuel.
- Further processing, where conversion units turn residue into lighter, higher-value products. These include cokers, visbreakers and residue hydrocrackers. Some refineries also use solvent deasphalting, which splits residue into a deasphalted oil and a hard asphalt fraction that can be used in bitumen blending.
Which outlet wins depends on refinery configuration, relative product values, unit capacity and existing contracts. A heavily upgraded refinery may produce little or no bitumen at all. This is one reason bitumen supply responds to fuel oil and crude markets, not only to road-building demand. It is also why regional bitumen price differences can open between origins.
Crude choices serve the whole refinery
Refiners select crude to suit their entire product slate and processing units. At many refineries, bitumen is a small share of total output. If a bitumen-yielding crude becomes expensive or unavailable, a refiner may switch to a lighter crude that suits its fuels business and accept lower bitumen output. That decision can make sense for the refinery as a whole, even when bitumen buyers are short of supply.
Contracted customers usually come first
When bitumen output falls, refiners typically allocate their remaining production to term customers before offering spot cargoes. As a result, spot availability can shrink faster than total production. Buyers who rely entirely on spot purchases tend to feel a feedstock shortage first. Our guide to term vs spot bitumen procurement explains the trade-offs between the two approaches.
What happens when heavy sour crude runs short: the 2026 example
Market reporting during 2026 illustrates these mechanisms. Since the US-Iran conflict began, disruption in the strait of Hormuz has tightened supplies of sour Middle Eastern crude into Europe and Asia. Each example below is labelled as a reported development or a market expectation. None of them are Tiger Bitumen forecasts.
Europe
- Germany (reported). Government data showed German bitumen output this year running below 2025 levels. Market reporting attributed part of the decline to tighter supply of sour crude grades since the conflict began.
- Czech Republic (reported). According to one buyer, bitumen made up a smaller share of output at a Czech refinery this year because bitumen-yielding Middle Eastern crudes had become scarcer. Reduced truck supply from that refinery contributed to tighter conditions in southern Germany.
- Italy (reported). Regional buyers and trading firms said bitumen output at one refinery had been curtailed by interruptions to Saudi sour crude supply. The refinery had also taken a cargo of lighter, sweeter West African crude, which yields less bitumen.
- Greece (expected). Traders expected bitumen output at one refinery to rise as more Middle Eastern crude arrived for processing. An incident at the refinery on 9 October left that outlook unclear at the time of reporting.
- Hungary (expected). Output is expected to increase when a fire-damaged crude distillation unit resumes bitumen production. This example concerns refinery availability rather than crude supply. It shows how changes in a unit’s status can shift regional output.
Asia
- Singapore (reported and expected). Market participants said refiners were unable to secure suitable crude feedstock to produce bitumen. They expected spot availability to remain limited, with most volumes allocated to term commitments. Maintenance at a major refinery was also reported to be reducing supply, which is a separate factor from feedstock.
- Thailand (reported). Refiners were reported to be operating at reduced rates because of limited crude feedstock. Some volumes could still be exported because domestic demand was slow.
What this meant for buyers (our interpretation)
Taken together, these reports point to:
- fewer spot offers from affected export hubs;
- firmer prices in those markets;
- more buyers looking at alternative origins.
Some buyers turned to nearby producers, as discussed in our article on Southeast Asia bitumen supply. Others considered cargoes from much further away.
How a feedstock shortage reaches the buyer?
The following points are general analysis of how feedstock shortages tend to affect buyers. They are not predictions for any specific market.
- Fewer spot cargoes. With output down and term customers served first, spot availability can fall quickly.
- Narrower choice. Refiners producing less bitumen may not offer every grade, packaging option or loading window they normally would.
- Closer attention to quality. When a refinery changes or blends crudes, the properties of its bitumen can shift, even within specification. Reviewing test certificates for each shipment becomes more important. Our guide to bitumen quality testing explains the key tests.
- Longer lead times. Buyers may need to commit earlier to secure volumes for a project schedule.
- Uneven regional pricing. Prices can firm in origins affected by the shortage while unaffected origins remain steadier. That can change which source offers the best landed cost.
Signals buyers can watch
Buyers rarely see a refinery’s crude purchases directly, but several signals can show when feedstock pressure is building or easing:
- Disruption to heavy sour crude flows, such as shipping restrictions, sanctions or production changes in major producing regions.
- Reports of refiners switching to lighter crudes, which usually means lower bitumen yields.
- Refinery maintenance, outages and unit restarts, which can change regional bitumen output independently of crude supply.
- Strength in fuel oil markets, which can draw residue away from bitumen.
- Changes in spot offers relative to term allocations from regular export suppliers.
- The seasonal calendar. Feedstock tightness during a peak paving season has a larger effect on buyers, as our seasonal bitumen demand guide explains.
Practical steps for international buyers
Feedstock shortages are outside a buyer’s control, but planning can reduce their impact:
- Qualify more than one origin and grade in advance, so an alternative is ready if a usual source tightens.
- Ask suppliers about supply continuity for the contract period, including whether volumes depend on a single crude source.
- Specify the standard and test methods clearly in contracts. Require a certificate of analysis for each shipment, and consider independent inspection.
- Cover base demand with term supply where consumption is predictable, and use spot purchases for flexible volumes.
- Build stock ahead of peak demand where storage allows, following good bitumen storage and handling practices.
Conclusion
Bitumen supply depends on a narrow range of crude oils. Heavy crudes generally leave the residue that bitumen is made from. Many of the most widely used bitumen-yielding grades are also sour, but not every heavy crude produces residue suitable for paving.
Refiners decide how much bitumen to make based on three factors: the crude they can obtain, their refinery configuration, and the value of competing outlets such as fuel oil. When suitable crude becomes scarce, bitumen output can fall quickly, and spot buyers usually feel it first.
The events reported in 2026 show how directly crude markets can shape bitumen availability. For buyers, understanding this link makes it easier to read early warning signs, diversify sources and plan purchases before shortages reach the project site.
Buyers reviewing their supply options can request a bitumen quote with their required grade, quantity, packaging and destination. This article is general commentary and does not constitute a price or availability offer.